The 1921 Book on The English Capital Market
According to Wright (1927: 504), Lavington’s work on the capital market was designed to fill in the details of ‘one corner of Marshall’s broad picture’ not effectively completed by him. The book drew considerably on material in Lavington’s three Economic Journal articles published before the war. It also commented on the subject of risk, a topic Lavington addressed in a two-part (1925, 1926a) Economic Journal article discussed later in this section. A note on sources acknowledged Lavington’s (1921 [1929]: 283) general indebtedness to Marshall’s and Pigou’s economic work. Looking at the references cited in Lavington’s book, none are dated after 1920. The 1929 printing contains only the Preface of the original 1921 edition, suggesting that it probably was a reprint corrected only for small errors. As Lavington had died two years before the issue of the 1929 reprint, this is not surprising.
The structure of The English Capital Market is as follows. The book is divided into four, very uneven, parts, with respect to size. Part I presents ‘Leading Ideas’ by way of a short introductory chapter; a discussion of the market for money, capital, and trade credit; concluding with a broad overview chapter, presenting a general view of the market. This presents the capital market as part of the specialization under a division of labour practised in a modern economy, designed to efficiently provide business with capital. Part II presents an outline of the theory of money in its six short chapters. Chapter V introduces the quantity theory of money as a supply and demand theory of the value of money. The demand for money is explained in Chapter VI, while Chapters VII-IX analyse the supply factors. Chapter X presents an overview. Part III of the book is devoted to ‘The Transport of Capital’. Its eight chapters analyse ‘The Flow of Resources into Investment’ (Chapter XI); ‘The Influence...of the Market on Waiting’ (Chapter XII); and on risk (Chapter XIII) including that from ‘Imperfect Knowledge’ (Chapter XIV); and the immobility of resources invested (Chapter XV). Chapter XVI looks at the marketing of securities, and Chapter XVII at the influence of the market on the demand for capital before closing with a review of marketing operations (Chapter XVIII). Part IV, well over half the size of the book, devotes its twenty-five chapters to the institutions which make up the English capital market. Nine chapters (Chapters XIX-XXVII) discuss the banking system and its role in the provision of currency as an essential feature of the market which assists the circulation of capital in a modern economy. Fifteen chapters (Chapters XXVIII—XLII) examine the stock exchange as a market for longterm securities. It includes the role of the speculator in that market, both in general and in terms of the specific operations of the London Stock Exchange. Chapter XLIII examines the role of trade credit as another aspect of the capital market. The final chapter (Chapter XLIV) presents conclusions.
Some general features of the book are highlighted first. Presentation of its argument is within the setting of the pre-1914 gold standard, with bullion stocks the major reserve underpinning the note issue. Secondly, the book is internationally comparative, referring to German, French, and the US, as well as English, practice. Despite the original year of publication (1921), as much of the factual material is pre-war if not end nineteenth century. These data are largely derived from The Economist, from official inquiries into the monetary system and from reference works equally divided between English and German language titles, and, to a lesser extent, French and North American sources. Lavington’s broad acknowledgement of work by Marshall and Pigou has already been mentioned.
Part II of The English Capital Market contains an outline of the theory of money, that is, a discussion of the theory of value of money based on supply and demand. The algebraic version of Lavington’s theory is the Fisherine form of the quantity theory:
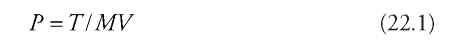
where P is the price level, T the volume of transactions, M the quantity of money, and V the average velocity of circulation. Lavington substitutes nr for the MV of the Fisherine form, where n is the practical equivalent of M (‘number of units of money’) and r that of V (‘the average velocity of its circulation’). Lavington explicitly depicted the theory as one of supply and demand, since his argument on the previous page identified P with D/S, where relevant demand factors explaining the value of money are indicated by T, the volume of transactions, while the relevant supply factors are the effective quantity of money, MV (Lavington 1921 [1929]: 23-24).
The next chapter explains the demand for money in terms of the distinction between ‘the yield of convenience’ in holding money and ‘the security’ associated with this action. Moreover, money’s ‘marketability’ (Lavington’s term for what would now be called ‘liquidity’) or general acceptability is part of its return for the holders of money, and explains why money is so attractive an asset to hold (ibid.: 30-31). There is no specific consideration of what became known as the Cambridge Cash Balance equation where the demand for holding money was directly related to the level of income of the holder and inversely to the rate of interest. Lavington (ibid.: 36-37) simply explained the supply of money by the instruments capable of acting as money (notes, coin, bank deposits in cheque accounts, bills of exchange drawn on secure borrowers, and, as was the case before the First World War, gold reserves and stocks of gold coin).
Lavington (ibid.: 65-66) then examined the role of the capital market from the perspective of Marshallian saving-investment analysis. Lavington (ibid.: 75-79) identified the term ‘waiting’ with both saving (postponement of, or waiting for, consumption) and investing (waiting for the output of production). Much space was devoted to the risk involved in these activities. Risk is explained by imperfect knowledge and uncertainty, a discussion in which Lavington (ibid.: 87-89) referred to Pigou’s treatment in Wealth and Welfare and to his own analysis in Lavington (1912). Moreover, risk is increased for certain investment by its degree of immobility. Marketability is therefore a valuable quality of an investment since it lowers risk for individual investors, and is an important service which capital market institutions render to investors through reducing risk. The supply price of capital is then explained (Lavington 1921 [1929]: 101) as comprising net interest, the price of risk bearing, and other costs of moving capital not specified by Lavington. How to reduce these costs is a specific task Lavington ascribed to the capital market, the analysis of which occupied much of the remainder of the book. This contains a detailed examination of the banking system, the stock exchange, and trade credit. On the basis of this analysis, the capital market can be depicted as an important additional agent of production, within the set which Marshall had called ‘organisation’.
Given their close association with risk analysis, Lavington’s (1925, 1926a) papers in the Economic Journal can be usefully reviewed here. Lavington (1925: 186-187) introduced risk as an indication that there can be no ‘perfect knowledge’ in the world as is, so that ‘complete calculation’ is impossible in business decision making. Undertakings of future events are by definition uncertain and are filled with risk or the ‘unrelieved probability of loss (ibid.: 187; italics in original).
Once again following J.B. Clark (in an unspecified source), Lavington (ibid.: 194) identified three costs associated with uncertainty, namely ‘(1) [Expenditure of the organizing capacity by which these losses [of uncertainty] are reduced; (2) [R]eduction in the real incomes of the producing parties as a result of the imperfect use of their productive resources; and (3) [R]eduction in the efficiency of individual incomes as a result of their uncertainty’. Lavington (ibid.) then examined payment for the bearing of risk and uncertainty using analytical apparatus developed by Pigou. This allowed him to argue that the growth of the firm tended to lower the costs attributable to uncertainty and risk; that stock prices set in the market reflected the costs of risk; and that risk reduced efficiency in using productive resources while uncertainty lowered the efficiency with which income can be used (ibid.: 195-198). Insurance cannot lower risk, only uncertainty for the insured, while costs attributable to risk can be said to fall on both producers and consumers alike (ibid.: 199).
In the second part of his paper, Lavington (1926a) appraised the following aspects of risk and uncertainty. Certainty of supply whenever that can be achieved considerably enhances consumers’ surplus. Lavington then argued that while losses arise from the incalculability of uncertainty, the additional expenses from specific risks are quite estimable. Moreover, much of the entrepreneurial task arises from problems associated with risk. Business risks are then identified with the possibility of war, insecurity of property, variable standards of value, and unstable tariff policies (ibid.: 201). Lavington illustrated this argument with a wheat/potato example, where fluctuations in output tend not to be offset (or neutralized) by opposite price changes. This phenomenon tends to make farmers’ incomes unstable, or as stable as if the prices of these commodities had been stable at their average level (ibid.: 202-203).

