Ramsey's Economics
Ramsey published only three articles in economics: as an undergraduate student of 18 years of age, he published a critique of Major Douglas’s credit theory for Ogden’s Cambridge Magazine in 1922; then in 1927 and 1928, he published two important articles in the Economic Journal, the first on taxation and the second on optimal saving.
Major Clifford Hugh Douglas did not complete his studies at Cambridge and became a member of the Institute of Electrical Engineers. Together with Alfred Richard Orage and others, he developed from the late 1910s (a period when the UK was off the gold standard) a theory of guild socialism known as the A + B theorem’ in which credit had a central role. Major Douglas saw money as a ticket system that granted the right to its owner participation in the economy, allowing the goods produced to be distributed to consumers as they see fit. Additionally, and central to his ideas, he conceived production as a multistage process in time, with firms distributing two types of payments: (A) payments to other firms related to the purchase of raw materials and to other costs; (B) payments to individuals in the form of wages, salaries, and dividends (Hutchinson and Burkitt 1997: Chapter 2). The prices of goods reflect both A’ payments made in the past and ‘B’ (thus A + B’), and in a given period of time, ‘B’ cannot buy A + B’ (though over time there is no lack of purchasing power). Therefore, extra money in the form of credit should be injected into the economic system every now and then. His argument was also made in terms of selling prices being inferior to cost prices of goods due to a lack of purchasing power.
According to Soifer (2009: 293), Ogden was the one who persuaded Ramsey to analyze Douglas’s proposals. Douglas’s writings are far from clear, and Ramsey opened his review article suggesting to those interested in understanding his ideas to read W Allen Young’s Dividends for All (Ramsey 1922b [1968]: 335). Young pointed to a flaw in Douglas’s theory, with an argument that in general terms involved the possibility of an existing firm producing intermediary goods and distributing wages and dividends that could absorb the surplus of all other firms. Ramsey set himself the goal of exploring this flaw in Douglas’s theory more carefully. Unlike Young’s static argument about the existence of purchasing power somewhere in the economy at a given point in time, and contrary to the understanding of Hutchinson and Burkitt (1997: 84), Ramsey went on to make a dynamic argument very much in line with Douglas’s stress on production as a multistage process in time. Ramsey (1922b [1968]: 336) made ‘a strong and simple argument for supposing that the [selling price to cost price] ratio does not differ appreciably from unity’: this ratio is equal to one in a ‘stationary state’, which is a state ‘in which production goes on at an unchanging rate and prices, wages and the national wealth never alter’ (ibid.). In this state, ‘the distribution of purchasing power by all [intermediary] factories proceeds at rate A’, which together with wages and dividends through B add up to an aggregate purchasing power of A + B—‘which equals the rate of flow of cost prices of consumable goods’ (ibid.: 337).
Finally, Ramsey closes his analysis with two arguments. The first is that ‘the present state is not very far from being stationary’ (ibid.), thus implying that the ratio of selling to cost prices does not differ greatly from unity. But he understood that this was not a general case. He then used integral calculus, and integration by parts, to study this ratio ‘under much wider conditions, which allow for changes in the quantity of production, in the rate of wages, in the productivity of labor, and in the national wealth’ (ibid.). With a dynamic analysis, he first showed that under certain conditions the ratio of selling to cost prices is unitary (ibid.: 337-339) and then considered even more general conditions. In this case, he showed two possibilities for the ratio to be less than one but they are ‘obvious to common sense and are clearly irrelevant to Major Douglas’ contention that “just price” is today a quarter of cost price’ (ibid.: 340).
The two papers that Ramsey published in the Economic Journal were the ones to secure him, eventually, a distinguished place in the economics profession. Contrary to the view that he was mostly a mathematician distracted by economists to help them with certain mathematical problems, I have argued elsewhere that those two papers were part of what we might call Ramsey’s research agenda in economics, which emerged from his close interaction with Pigou (Duarte 2009a). As part of a Cambridge habit of senior Fellows asking other economist Fellows to help them with their research, Pigou involved Ramsey in his work that culminated with the publication of his 1928 book A Study in Public Finance, with a concern about tax exemption on savings.[1] Out of this concern, Ramsey first wrote an article setting up a static utilitar?ian framework for characterizing the optimal tax rates for a government in need of raising revenues at the same time that it does not have lump-sum taxes available. Ramsey (1927) simply postulated that there exists a net utility function of producing and consuming quantities of n goods in the economy (denoted by x): u = F(xj...xn) . He then showed that uniform taxation is generally suboptimal because the tax rates that maximize this function are those that reduce the production of all taxed commodities in the same proportion with respect to the benchmark of prices equal to marginal costs. Not surprisingly, Pigou was the first to cite Ramsey (1927) in his 1928 book, stressing the elasticity version of Ramsey’s result already enunciated by the latter: inelastic commodities, either for supply or for demand, should be taxed more than elastic ones.
As a reaction to Pigou’s ‘treatment of saving as a use of income with its own elasticity of demand’ (Ramsey quoted in Duarte 2009a: 463) in the 1928 book, Ramsey (1928) built on his previous article to discuss the taxation of savings in an intertemporal utilitarian framework. He first characterized the choice of savings that maximizes the utility of consumption net of the disutility of labor subject to the economy’s resource constraint (which specifies that expenditures on consumption and investment exhaust aggregate output). In the first part of his article, he discusses the savings problem of a society without discounting future utilities on ethical grounds of intergenerational justice. Thus, in order to have a well-defined optimization problem, Ramsey postulated the existence of an upper bound to net utility and therefore minimized the distance over time of the actual utility to this bliss level:
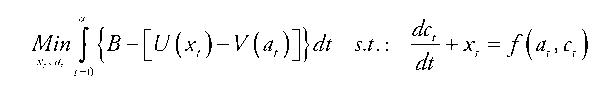
where B is the bliss level, and xt, at, and ct are respectively consumption, labor, and the stock of capital.
The solution to this problem specifies that ‘the saving rate multiplied by marginal utility of consumption should always equal bliss minus actual rate of utility enjoyed’ (ibid.: 547).[2] Keynes suggested a marginal approach (of equating cost and benefit at the margin of saving one extra unit of money today) as an alternative way of deriving Ramsey’s mathematical result, as Ramsey acknowledged in the article—a result nowadays referred to as the
‘Keynes-Ramsey rule’. Once again, Pigou was the first to cite Ramsey (1928) in the second edition of his public finance book, published in 1929.
However, the published version of the 1928 paper has no section analyzing taxation. After Ramsey submitted the article to the Economic Journal, Keynes asked him to cut the section on taxation out of the optimal savings article as the mathematical analysis was ‘too involved in comparison with the conclusions which were feeble’ (Ramsey quoted in Duarte 2009a: 463). Ramsey agreed with Keynes and accepted his suggestion. The draft of the original section survives and was published in 2009 (Duarte 2009c).
What is clear from the few contributions by Ramsey to economics is both how his research agenda emerged out of the Cambridge milieu of his time and how concerned he was with using economics to obtain general results useful to improving human well-being. For the two later articles, Pigou was instrumental in posing the questions, providing an analysis against which Ramsey reacted, and in citing the articles in an important book of the interwar period. Keynes was important, too. He had Ramsey as an interlocutor to try out his ideas and to consult about articles submitted to the Economic Journal (Duarte 2009a: 455-456). Moreover, he helped shape the argument of Ramsey’s 1928 article and stressed that rendering sound results should limit the complexity of mathematical analysis in economics.
- [1] Pigou asked for Ramsey’s help in preparing the third edition of his book Economics ofWelfare, publishedin 1929, as he had done earlier with the young Keynes, who helped revise his 1912 Wealth and Welfare(Duarte 2009a: 459). See Gaspard (2003) for a discussion of Ramsey (1928).
- [2] Later in the article, Ramsey considers the optimization problem of an individual who discounts futureutility and shows how this result has to be adapted accordingly.

