Growth and Distribution
When he returned to academic life in late 1949, at the age of 41, Kaldor was in mid-career. He was well known and well respected as an original theorist in both microeconomics and macroeconomics and had also made significant contributions in applied economics and to policy debates. His first major paper as a Cambridge economist was devoted to his original and controversial macroeconomic model of income distribution. It appeared in 1956, the same year as Joan Robinson published her magisterial (but seldom read) Accumulation of Capital, and has to be seen as part of the Cambridge project to ‘generalise The General Theory by extending Keynesian macroeconomics to the long period and replacing the remaining elements of Marshallian theory with something that was not subject to the logical defects that were beginning to emerge in the neoclassical theory of capital (see the Chapters 27, 30 and 31 in this volume).
In his distribution paper Kaldor explicitly repudiated both the marginal productivity of relative shares and Michal Kalecki’s degree of monopoly theory (which he regarded as tautological). His own model was explicitly Keynesian in its focus on the relationship between investment, saving, and the share of profits in national income that was required for macroeconomic equilibrium.
It had been foreshadowed by Keynes himself in the well-known ‘widow’s cruse’ parable in the Treatise on Money and also by Kalecki in a wartime article (Kalecki 1942), and something similar was hinted at in Robinson’s book. But the details of the model were original to Kaldor.
In a simple two-class Keynesian model with no foreign sector and no government, in which investment (I) drives saving (S), and the savings propensity of the capitalists (sc) is greater than that of the workers (sj, the profit share is determined by the ratio of investment to income and the share of wages is a residual. In the simplest case, where workers save nothing (so that sw = 0), macroeconomic equilibrium requires that
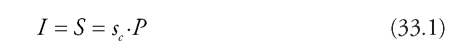
where P is total profits. Dividing both sides of Equation (33.1) by Y and rearranging terms, we have
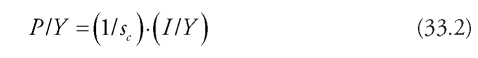
In Kaldor’s own numerical example, IIY= 20%, sc = 0.5, and the profit share P/Y= 40% (so that the wage share, W7Y is 60%). Since nothing is saved by wage earners, capitalists must get 40% of total income so that, when they save half of it, savings and investment are both equal to 20% of Y. If I/Ywere to rise to 21%, the profit share must increase to 42%, and the wage share must fall to 58% (Kaldor 1955-1956: 96, fn. 2). If the propensity to save out of wages is positive (or negative, as in the lead-up to the sub-prime mortgage crisis in the USA in 2006-2007), Kaldor’s algebra is slightly more complicated, but the underlying principle remains the same.
It is, however, subject to a rather obvious difficulty. If workers save, they also acquire capital, from which they derive an income, but no account is taken of this additional income in Kaldor’s algebra. In 1962, Luigi Pasinetti showed that this problem could be overcome by a simple reformulation of the model, leaving the underlying Kaldorian conclusion unchanged: relative income shares still depend on the ratio of investment to income and on the capitalists’ propensity to save. The workers’ propensity to save is irrelevant, whether they have income from ownership of capital or not (Pasinetti 1962). An extensive literature emerged on the Kaldor-Pasinetti macroeconomic distribution theory, much of it by Italian scholars, extending the model to an open economy with a government sector and with rentiers as well as capitalists.
The microeconomic implications also began to be teased out, with the appearance of oligopoly pricing models in which the size of the markup over variable costs of production was determined by the company’s need for retained earnings to finance its investment plans (see Chapter 9 in this volume).
This points, however, to an empirical problem with the Kaldor-Pasinetti model. It is best suited to a world of managerial capitalism, characterised by the separation of ownership and control, in which the behaviour of the modern corporation can be summarised as: ‘retain and reinvest’. This is the world described by Berle and Means in their classic The Modern Corporation and Private Property (1932), published at a time when the power, prestige, and moral authority of financial markets were at an all-time low, and the autonomy of professional managers was correspondingly large. In the twenty-first century, financialisation—more accurately, the continuing process of refinancialisation that began in the 1970s—has undermined this autonomy, restoring ‘shareholder value’ as the driving force underpinning corporate behaviour and enforcing a new guiding principle: ‘distribute and downsize’. Macroeconomic equilibrium still requires that Equations (33.1) and (33.2) be satisfied, but the causal relationships between the variables are no longer obvious.
The profit share has in fact increased in almost every advanced capitalist economy since about 1980, but this has not been the result of a sustained increase in IIY; instead, sc has decreased—a possibility not seriously considered by Kaldor, though the reverse phenomenon (increased working class militancy generating a rising wage share and a corresponding increase in sc) had been suggested by Maurice Dobb (1929). Institutionalists and Marxians would conclude from all this that Kaldor had ignored the broader social and political determinants of class shares, which in practice were more important than the abstract macroeconomic relations that he had emphasised.
None of this was obvious in 1957 when Kaldor published his first formal model of economic growth. This was his initial contribution to the ‘generalisation of The General Theory to the long period by tracing out the implications of positive net investment and the resulting increase in the capital stock. The Oxford economist Roy Harrod (1939) had led the way with his demand-driven (more precisely, investment-driven) growth model, in which the ‘warranted’ (or equilibrium) rate of growth (gw) depended on the ratio of investment (and hence saving) to income (s) and the technically determined ratio of capital to output (v) : gw = s/v . However, the maximum or ‘natural’ rate of growth (gn) depended on two supply-side factors, the rates of growth of population and of labour productivity, with the latter being determined exogenously by technical progress. Harrod noted that there was no guarantee that gw would be equal to gn, or that either would equal the actual growth rate (g). He concluded that any initial inequality between gw gn, and g would give rise to substantial and continuing macroeconomic instability in the form of steadily rising unemployment or accelerating demand inflation. This was the notorious ‘Harrod knife-edge’.
In practice, capitalist economies were not wildly unstable, and Kaldor believed that his distribution model helped to explain why. The aggregate savings propensity (s) was not constant, as Harrod supposed, but variable. As we have seen, for Kaldor it was closely related to the distribution of income, and in his 1957 growth model changes in the shares of wages and profits served as an indispensable source of macroeconomic stability. In other respects, Kaldor’s model was similar to Harrod’s. They were both one-sector models, with no distinction being made between agriculture, manufacturing, and services, and they both assumed a closed economy. Unlike the canonical neoclassical Solow-Swan model, first published in the previous year (Solow 1956; Swan 1956), in Kaldor’s 1957 model growth was demand-determined, with investment driving savings rather than savings driving investment. There was no aggregate production function, no question of capital-labour substitution in response to relative prices, and hence no possibility of v being variable, which was the mechanism that provided stability in the neoclassical growth model.
In one crucial respect, however, Kaldor broke with Harrod. He argued that technical progress was endogenous: it depended on investment, through what came to be known as the ‘vintage effect’ (referring to the superiority of old wine and new technology). The higher the ratio of investment to income, Kaldor maintained, the lower the average age of the capital stock and the greater the proportion of machines that embodied more recent, and therefore more productive, technology. Kaldor introduced a ‘technical progress function’ that made productivity growth a positive function of IIY and gave an additional reason to expect macroeconomic stability, since an increase in gw could now be expected to induce a corresponding increase in gn. He went even further, claiming that sustained growth was consistent only with continuous full employment, a strangely anti-Keynesian notion that led Paul Samuelson to describe him sardonically as ‘Jean-Baptiste Kaldor’.
Kaldor was no mathematician, and his 1957 growth model was itself a low-tech affair, which must have contributed to the neglect that it suffered outside Cambridge. Five years later, he published a much more sophisticated version, the mathematics being provided by his young co-author, the future Nobel Laureate James Mirrlees. Kaldor’s 1962 model made an even sharper break with neoclassical growth theory, since there was no longer any mention of the capital stock, only its rate of increase: everything now depended on the rate of investment. Possibly this reflected the influence of Sraffas Production of Commodities by Means ofCommodities, which had appeared two years previously and cast serious doubt on the coherence of neoclassical capital theory. By this time, Kaldor had fallen out with Joan Robinson, whom he now accused of being excessively neoclassical in her own approach to the theory of growth.
In one respect, though, he was becoming dissatisfied with his own analysis. The 1962 model, like that of 1957, was a one-sector affair, and this seemed to Kaldor to shed little light on the poor growth performance of the post-war British economy by comparison with the rapid growth that had been achieved in many parts of Continental Europe. In his 1966 Inaugural Lecture, Causes of the Slow Rate of Economic Growth of the United Kingdom, he developed what was effectively a third model of economic growth, now emphasising the crucial difference between the primary and secondary sectors. The British economy had matured early, he argued, in the sense that primary production now accounted for a very small proportion of total employment, and the scope for productivity gains by transferring labour from agriculture to industry was correspondingly low. This meant that manufacturing output was growing more slowly in Britain than in countries like France, West Germany, and Italy, where there remained a large reservoir of low-productivity agricultural labour that could move to industrial employment. This was a very important point, since there were dynamic increasing returns to scale in manufacturing, as revealed by Verdoorn’s Law (discovered by Kaldor’s former colleague at UNECE, the Dutch economist PJ. Verdoorn): productivity growth is a positive function of the rate of growth of output. So the relatively immature Continental economies were enjoying much faster productivity growth than was possible in Britain, or for that matter in the USA.
Kaldor’s 1966 model was not recognisably Keynesian, and indeed it was almost neoclassical in its emphasis on the supply of labour to manufacturing industry as the fundamental constraint on growth. It was also once again an informal, low-tech affair, almost devoid of algebra, but (he believed at the time) both more realistic and more useful than his earlier efforts had been. Once again, however, he soon became dissatisfied with it. This time he focused on its neglect of the external sector. By 1970 Kaldor had come to see exports as the only genuinely exogenous source of effective demand and the balance of payments as the binding constraint on growth. This reflected his frustrations as an adviser to the British government after 1964, where recurrent balance-of-payments difficulties gave rise to a ‘stop-go’ economy, and characteristically he never developed the arguments in any systematic way. However, the subsequent formalisation of Kaldor’s insights by John McCombie and Tony Thirlwall has generated a substantial international literature on balance-of-payments-constrained growth.
Two final points should be noted in relation to Kaldor’s growth models. First, they anticipated what later came to be known in the mainstream literature as ‘endogenous growth’ theory, and he is sometimes given credit for this by economists who are otherwise unsympathetic to his approach to economics more generally. Second, they have significant implications for the analysis of economic development on a global scale, as Kaldor acknowledged in the ‘North-South models’ that he produced in the final decade of his life.

